Spring has sprung, and with it comes a fresh opportunity for property sales. The months of March through May are historically the prime time for the property market, yielding consistent sales each year1. If you’re contemplating a sale, here are five compelling reasons to make Spring the season to showcase your property on the market.
1. A Surge in Buyer Interest
Spring’s pleasant climate brings out numerous prospective buyers, creating a high demand for available properties. As a seller, this can make for the ideal time – increased interest from potential buyers, which can lead to more competitive offers and quicker deals being done as buyers seek to secure their dream home before someone else does.
2. Spring: A Time for Renewal and Relocation
There’s something about Spring that ignites the desire for a fresh start. This transformative period, symbolised by budding trees and blooming flowers, mirrors the aspirations of many to commence new chapters in their lives. For those tired of their existing homes, it may provide the trigger to look for something new – creating a swarm of eager buyers planning life-changing moves, from upgrades to relocations.
3. Enhanced Kerb Appeal
With Spring’s promise of better weather and longer days, properties naturally present themselves in the best light. The exteriors of homes bask in the seasonal glow, making architectural details stand out and inviting more foot traffic for viewings. This period is ripe for showing off not just homes with gardens but also those near vibrant communal spaces or with balconies that can be adorned with colourful blooms.
4. Ideal Lighting for Showcasing Interiors
Just as the exteriors benefit from Spring’s light, so do interiors. The season’s bright, natural light is perfect for capturing stunning photographs of your property’s interior, crucial for attracting online browsers and when it comes to the property viewings, can potentially help play a part in turning a prospective buyer into someone making an offer.
5. More Favourable Moving Conditions
Practically speaking, Spring’s moderate climate makes the moving process itself more bearable compared to the winter’s chill or the summer’s swelter.
Before you leap into the Spring market, ensure your property is at its most presentable. A thorough clean, some strategic decluttering, and a touch-up here and there, like a fresh coat of paint on the front door, can make a significant difference. Remember, first impressions are vital.
All the information in this article is correct as of the publish date 25th April 2024. The opinions expressed in this publication are those of the authors. The information provided in this article, including text, graphics and images does not, and is not intended to, substitute advice; instead, all information, content and materials available in this article are for general informational purposes only. Information in this article may not constitute the most up-to-date legal or other information.
A Cambridge University study once found that a person’s financial habits were established by the age of just 7, so we look at some ways that could get kids off to a flying start1.
Pocket money saving
In days past, it was likely that most children were granted pocket money each week – often cash rewarded in exchange for chores completed, and helped to give kids a good understanding of how money works and how to manage the money they receive from a young age – skills that will hopefully last them throughout life.
As children get older, moving away from the piggybank, one option to consider could be bank accounts, where a range of savings options exist:
Debit card – a prepaid debit card could provide a means of introducing children to personal finance. As they familiarise themselves with the digital world of banking, being able to show them how to instantly check the balance on their card together with the convenience of being able to top it up easily, will help a parent or carer give a child more confidence in managing their money.
Current account – this option could be used for storing pocket money or earnings from part-time jobs (from the age of 16 upwards), and provide a further means of saving and spending money aside being reliant on cash. It’s important to bear in mind terms and conditions from the bank providing the current account service before setting it up.
Savings account – if there is a considerable amount of funds saved, then there are options around a savings account or ISA, which may hold additional benefits in terms of interest rates or taxation further down the line when children are older. It’s always recommended to seek independent financial advice before making a decision.
Methods like these can all be of valuable assistance in the effort to help children understand the importance of managing money from an early age, and hopefully set them up well for the financial decisions they will make in the future.
All the information in this article is correct as of the publish date 28th March 2024. The opinions expressed in this publication are those of the authors. The information provided in this article, including text, graphics and images does not, and is not intended to, substitute advice; instead, all information, content and materials available in this article are for general informational purposes only. Information in this article may not constitute the most up-to-date legal or other information.
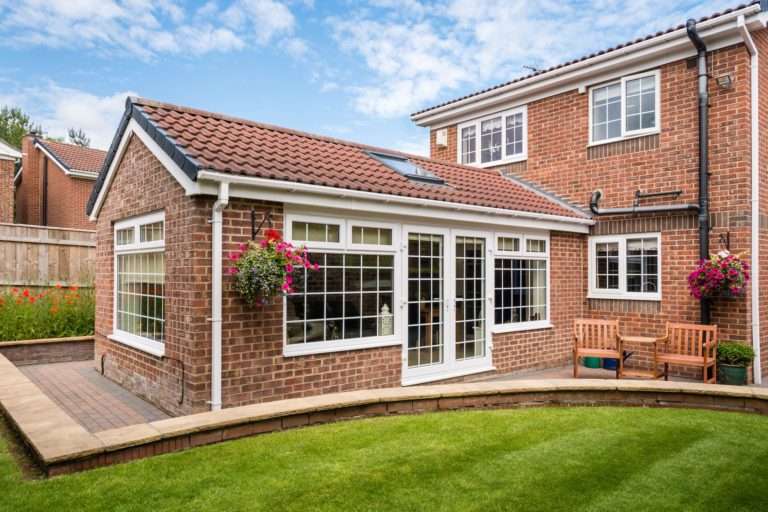
If you and your family are thinking of needing extra space – the natural thought can be to simply search for a new property. However, with the turbulent housing market and rising cost of mortgages – one answer might be right under your feet.
Adding Value to Your Home
Not only can a home extension offer the much-needed space, but it can add some real value to your home in the process too. A survey by Checkatrade revealed that an extension can add between 5-8% to your property value, depending upon the size, style and design of the extension itself1.
However, before getting started with the building tools, it’s wise to do a little research on the key considerations to be had when embarking on an extension project.
Planning Permission
Depending on the size and location of your planned extension, you may or may not need planning permission from your local council. There are permitted development rights allowing some single-storey rear extensions to be built without the need for consent. However, it’s important to check the specific measurements and regulations to ensure your extension complies.
Building Regulations
Even if you don’t need planning permission, building regulations approval will still be required. The extension must meet minimum standards for structural integrity, insulation, electrical safety and so on. Using a qualified builder can help ensure regulations are followed.
Inform Your Insurer
Let your home insurance provider know about your extension plans, as this could affect your cover during the works and once completed. Additional rebuild costs may increase your premiums too.
Speak to Your Neighbours
Be considerate and talk through any disruption the works could cause. You may also need neighbours to agree to plans if building on shared walls or boundaries under Party Wall laws. Maintaining good relations is key.
Finding the right Architect & Building Firms
This is arguably the most important decision. Do your research to find an experienced and trustworthy builder or architect. Get recommendations and read reviews. Make sure they have the specific expertise you need.
Get Multiple Quotes
To achieve the best value, get at least three itemised quotes from different builders outlining the full costs. Compare these in detail before selecting who to hire.
Hopefully these tips give you a good overview of key things to consider at the start of your extension journey. It certainly pays to conduct proper planning early on to smooth out and manage the key processes in an effective way – and to turn your place into your dream home, without having to move properties.
All the information in this article is correct as of the publish date 29th February 2024. The opinions expressed in this publication are those of the authors. The information provided in this article, including text, graphics and images does not, and is not intended to, substitute advice; instead, all information, content and materials available in this article are for general informational purposes only. Information in this article may not constitute the most up-to-date legal or other information.
With growing frustration surrounding NHS waiting lists and difficulties accessing care, more individuals are considering private healthcare. In this article, we explore the merits of private health insurance and whether it may be a viable option for you.
The Rising Trend of Private Healthcare
Recent data from the Private Healthcare Information Network (PHIN) shows 272,000 people in the UK opted to self-fund medical procedures or diagnostics at private hospitals last year – a significant 33% increase compared to pre-pandemic figures1. Over double that number relied on private medical insurance policies to cover expenses1. While private health insurance can provide quicker access to care, it’s essential to weigh the costs against the benefits and understand policy limitations and exclusions.
Understanding Private Medical Insurance
Private medical insurance generally offers swift access to healthcare services like assessments, diagnoses, treatments, and aftercare. You often can select your preferred specialist and private hospital location. Many providers now extend support for mental health issues in addition to physical health.
Coverage Details: What to Expect from Private Health Insurance
Coverage varies between providers and plans, but often includes:
Consultations with specialist doctors
Inpatient treatment like surgeries
Outpatient services such as scans, tests, x-rays
Limited physiotherapy sessions
24/7 medical helplines and virtual GP appointments
However, typical exclusions may include:
Emergency treatment, which should be sought from your GP or emergency services.
Maternity care, which typically isn’t covered.
Chronic conditions like arthritis or diabetes treatment.
Beyond Private Health Insurance: Exploring Other Financial Safety Nets
Private health insurance isn’t the only policy that can provide financial support during health challenges. Critical illness insurance pays out a lump sum upon diagnosis of covered conditions, while life insurance provides a lump sum in the event of your passing during the policy term. Alternatively, income protection offers monthly benefits if illness or injury prevents you from working.
Making the Choice: Is Private Health Insurance Right for You?
The decision to invest in private health insurance hinges on your individual circumstances and preferences. If you’re concerned about long NHS waiting lists, then private health insurance may be able to provide greater peace of mind, however, if you have confidence in the NHS’s availability when needed, then this may be less of a priority for you.
Strategies for Self-Employed Individuals
For self-employed individuals, private health insurance can be crucial to ensure that health issues or accidents don’t disrupt your income. If you prefer to have the option to use private care but don’t want to purchase insurance, it may be worthwhile setting aside savings to cover potential medical expenses, should the worst happen. However, be mindful that medical treatments can be costly, and savings may not always suffice.
Private Health Insurance: A Personal Decision
The decision to invest in private health insurance is a personal one, dependent on your own circumstances and priorities. It’s important to weigh up the pros and cons carefully and explore the available options to make an informed choice that suits your needs.
Finding the Right Fit for Your Healthcare Needs
We can help you assess the range of insurance and protection products available and can help you source the most appropriate product to suit your needs, goals, and budget.
All the information in this article is correct as of the publish date 25th January 2024. The opinions expressed in this publication are those of the authors. The information provided in this article, including text, graphics and images does not, and is not intended to, substitute advice; instead, all information, content and materials available in this article are for general informational purposes only. Information in this article may not constitute the most up-to-date legal or other information.
Moving home is a significant life event, and ensuring a smooth transition requires attention to detail and meticulous planning. If you’re thinking of moving, we’ve compiled an extensive checklist to assist during the moving process.
1. Career-Related Notifications
Employer: Inform them for updated payroll and contact details.
HM Revenue & Customs (HMRC): Essential for tax-related updates. Visit gov.uk for instructions.
National Insurance: Update your NI information using your NI number. Check online for contact details.
2. Local Authorities and Governmental Entities
Council Tax: Update your address via the relevant gov.uk site.
Department for Work and Pensions: Notify them if you’re receiving government funds.
3. Recreational Considerations
Local Subscriptions: Cancel memberships to local gyms or clubs.
Postal Subscriptions: Update them with your new address.
4. Household Utilities and Services
TV and Broadband: Notify them of your move for billing and service adjustments.
Telephone: Update both landline and mobile providers.
TV Licence: Update your licence at the TV Licensing website.
DVLA Driving Licence: Update your driving licence address online.
Vehicle Breakdown Cover: Update your details with your provider.
Vehicle Insurance: Advise of your new address, be prepared for potential cost changes, insurance is graded based on risk rating at your new property.
V5C Vehicle Log Book: Update the address on your V5C at the Government website.
5. Educational Institutions
Schools: Notify them if you have children for contact information updates.
Universities: Inform them of your move for record updates.
6. Insurance Policies
General Insurance: Update address details for various policies like health, home, life, travel, and pet insurance.
7. Services Providers
Maintenance Services: Cancel or update addresses for gardeners, window cleaners, etc.
8. Financial Institutions
Banks and Building Societies: Update your residence address.
Premium Bonds: Ensure your address is current for receiving any winnings.
Pensions: Contact your pension provider with the new address.
Loan and Credit Card Companies: Notify them of your change of address.
9. Utilities
Electricity and Gas: Notify providers and take meter readings on moving day.
Water: Inform your provider about your moving date.
10. Settling Into Your New Home
Postal Redirect: Set up a redirect with Royal Mail for any mail to your old address.
We hope that this comprehensive checklist can help to make the moving process as smooth and as stress-free as possible, and by updating your address with all relevant parties as soon as you can, should help to minimise future complications or delays in services as you move into your new home.
All the information in this article is correct as of the publish date 25th January 2024. The opinions expressed in this publication are those of the authors. The information provided in this article, including text, graphics and images does not, and is not intended to, substitute advice; instead, all information, content and materials available in this article are for general informational purposes only. Information in this article may not constitute the most up-to-date legal or other information.
2024 is set to be a busy time for many homeowners, with the initial fixed term periods on mortgages expiring for a lot of clients across the market1, leading to some big decisions being required on remortgaging options.
What happens when your initial mortgage period expires?
Your initial fixed-term period will often expire after two years or five years, depending upon the specific deal, and after this, you’ll be put onto your mortgage lender’s Standard Variable Rate (SVR)2.
As you may be aware, the interest rates on the SVR may be higher than those that you can obtain with a fixed-rate deal2, so it’s always worthwhile taking action ahead of your fixed-term period expiring, to ensure that you’re not paying more than you need to, and that you’ve got a mortgage deal that fits your exact circumstances.
With interest rates having risen considerably in recent times, it’s also highly likely that the mortgage deals you will come across may be significantly higher than your existing deal, so there’s a lot at stake to ensure that you’re getting a fair rate when it comes to your renewal.
Remortgage or Product Transfer?
How does it all work? Ahead of your mortgage’s fixed-term period coming to an end, we’ll get in touch with you to discuss the options available to you, but to summarise, there is often a choice between a full remortgage, or a product transfer.
A product transfer is simply switching from one mortgage product to another, at your same lender. This is often a straightforward process and allows you to take advantage of some of the fixed-rate deals available from your existing lender, to prevent you going onto the Standard Variable Rate.
However, in some cases, there may be other deals available from other lenders in the market that are more suited to your current circumstances, and to access these would require a remortgage.
The remortgage process take longer, and is similar to that of when you first applied for a mortgage3. There would be evidence required of your earnings and property valuations undertaken, with more chance of fees payable to lenders, however, some may find that this inconvenience is offset through accessing deals that could possibly save more money and be of greater fit to your ever-changing circumstances.
How to know what’s most appropriate for you
It’s not always easy to know what’s right for you and your circumstances, so that’s where the value of professional mortgage advice comes in. We’re here to listen to your exact situation and to recommend the products that we believe are the most appropriate for you based upon looking at a wide range of lenders and exclusive deals that aren’t available on the high street.
It’s highly likely that your own lender will also reach out to you with offers of product transfers, however we would always recommend that you seek our experienced, professional advice before taking up any offers to ensure that these work in your interest as well as theirs. We’re more than happy to arrange both product transfers and remortgages, but pride ourselves in listening to your exact situation before giving bespoke advice that’s tailored to you.
Think carefully before securing other debts against your home. Your home may be repossessed if you do not keep up repayments on a mortgage or other debt secured on it.
All the information in this article is correct as of the publish date 30th November 2023. The opinions expressed in this publication are those of the authors. The information provided in this article, including text, graphics and images does not, and is not intended to, substitute advice; instead, all information, content and materials available in this article are for general informational purposes only. Information in this article may not constitute the most up-to-date legal or other information.
We use cookies to improve your experience and analyse website traffic. You can accept all cookies or manage your preferences.
Functional
Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes.The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.